-
When Will the Russian Sanctions End? Key Factors and Scenarios for the Future
Since Russia’s invasion of Ukraine in 2022, a comprehensive and far-reaching sanctions regime has been imposed by Western governments, aiming to weaken Russia’s economy and political elite. Over two years later, these sanctions remain firmly in place.
The upcoming U.S. election will play a pivotal role in determining whether the current sanctions regime continues, is modified, or even lifted. But beyond domestic politics, several global factors must align before we see any significant movement towards the end of Russian sanctions. In this blog entry, we will explore what might need to happen for the sanctions regime to end, including the potential outcomes of the ongoing conflict in Ukraine, shifts in global diplomacy, and the role of international economic interests.
1. The Role of the Ukraine Conflict
At the core of the sanctions regime against Russia is its ongoing military actions in Ukraine. The most immediate condition for the lifting or reduction of sanctions is a resolution to the conflict that is acceptable to both Ukraine and the international community. This could take the form of a formal peace agreement, a ceasefire, or other diplomatic solutions that indicate a significant de-escalation of hostilities.
However, the exact terms of such an agreement are critical. Western nations, led by the U.S. and European Union, are unlikely to lift sanctions without assurances that Russia respects Ukraine’s sovereignty and withdraws from occupied territories. The annexation of Crimea in 2014 remains a contentious issue, and any lasting peace will likely require addressing these territorial disputes, which complicates the path toward lifting sanctions.
Additionally, Ukraine and its Western allies have pushed for reparations and war crime accountability. If Russia agrees to such demands, the sanctions could be gradually eased. Conversely, continued aggression or unwillingness to compromise could solidify sanctions for the long term.
2. A Change in Russia’s Leadership or Political Landscape
Another key factor that could lead to the lifting of sanctions is a significant change in Russia’s political leadership or internal policies. The current regime, under President Vladimir Putin, has shown no signs of backing down, and the sanctions are aimed largely at crippling the financial networks supporting Putin’s government and his inner circle.
A leadership change could come through several possible scenarios:
- Internal political shifts: If domestic unrest or political opposition gains enough momentum within Russia to force changes in leadership, this could result in a more diplomatic stance toward the West and the potential for peace negotiations.
- Regime collapse: A more drastic and unlikely scenario could involve the collapse of Putin’s regime, either due to internal dissent, economic hardship caused by sanctions, or international isolation.
While regime change does not guarantee a shift in foreign policy, a new government more willing to negotiate with the West could lead to a recalibration of relations and a pathway to lifting sanctions. However, any new leadership would likely have to demonstrate a clear break from the policies that led to the sanctions in the first place.
3. Global Economic and Political Realignments
Geopolitical shifts beyond Russia’s borders could also influence the future of sanctions. Changes in leadership in Western countries or a realignment of international priorities might lead to different stances on the sanctions regime. For instance, if the political landscape in key sanctioning nations like the U.S., UK, or EU shifts toward leaders or governments that prioritize de-escalation over punitive measures, the sanctions could be eased as part of a broader diplomatic strategy.
Moreover, international organizations such as the United Nations or regional blocs might play a role in brokering agreements that could influence the sanctions landscape. If there is a global push for diplomatic solutions to address not just the Ukraine conflict but wider geopolitical tensions involving Russia, a more unified approach could lead to sanctions being lifted.
The global economic environment may also play a part. As the impact of sanctions ripples through global energy markets and economies, certain countries may seek to negotiate with Russia to stabilize these markets, which could lead to selective easing of sanctions in areas such as energy or trade.
4. Russia’s Economic Adaptation
Interestingly, the Russian economy has shown some resilience in the face of Western sanctions, as Russia adapts to new economic realities by strengthening its relationships with non-Western nations, including China, India, and other Global South countries. If Russia continues to develop these economic alliances, it may reach a point where the impact of Western sanctions is significantly diminished. In this scenario, the leverage that sanctions provide could erode, reducing their effectiveness as a tool of international pressure.
If Russia manages to build a parallel economic system that bypasses Western financial networks and trade routes, the motivation for maintaining the current sanctions regime might weaken, especially if they no longer achieve their intended economic or political objectives.
5. Humanitarian Considerations
The humanitarian toll of sanctions cannot be ignored, particularly if they begin to disproportionately affect ordinary citizens rather than the intended targets within Russia’s political and business elite. If sanctions contribute to a severe humanitarian crisis in Russia, there may be increasing international pressure to ease sanctions for humanitarian reasons, such as lifting restrictions on food, medicine, and other essential goods.
International bodies like the United Nations, human rights organizations, and non-governmental organizations could advocate for a partial rollback of sanctions if they argue that the suffering of civilians outweighs the political benefits of maintaining the punitive measures. This could lead to selective lifting of sanctions, even if the broader geopolitical issues remain unresolved.

6. Incremental Lifting of Sanctions
It is also possible that the sanctions regime will not end abruptly but will be lifted incrementally based on specific conditions being met by Russia. For example, Western governments may choose to ease certain sanctions related to trade or energy exports in exchange for partial troop withdrawals or other steps toward de-escalation in Ukraine. This kind of phased approach could serve as a diplomatic tool, encouraging compliance with international demands while keeping pressure on Russia to continue its retreat from aggressive policies.
Such an approach would allow for flexibility in international relations, with the option to reimpose sanctions if Russia fails to meet its obligations. However, it also presents the risk of “sanctions fatigue,” where countries become less inclined to maintain punitive measures over extended periods.
Conclusion
While the end of the Russian sanctions regime is contingent on several factors, the reality is that there is no quick resolution in sight. As long as the Ukraine conflict persists, and Russia’s leadership remains committed to its current policies, the sanctions are likely to remain a critical component of the West’s strategy. The potential for easing or lifting sanctions will depend on diplomatic breakthroughs, changes in Russia’s political landscape, or shifts in global economic and geopolitical priorities.
For now, the international community will continue to monitor developments closely, balancing the need to maintain pressure on Russia with the recognition that sanctions are only one part of a broader strategy to resolve a deeply complex conflict.
-
Sanctions and Politically Exposed Persons (PEPs) in 2024
Sanctions have long been a powerful tool in international diplomacy, used to pressure individuals, organizations, and countries involved in illicit activities, human rights abuses, or corruption. In 2024, the enforcement of sanctions has intensified, with a particular focus on Politically Exposed Persons (PEPs) and asset tracing. The global sanctions against Russia, following its invasion of Ukraine, have drawn particular attention as governments work to track and recover the assets of Russian oligarchs and officials. However, while many sanctions are effectively applied to individuals closely tied to the Kremlin, there have also been significant cases of wrongful targeting and misidentified assets, illustrating the challenges and complexities of the asset recovery process.
Understanding Sanctions and PEPs: The Basics
Sanctions are restrictive measures imposed by governments or international bodies aimed at coercing or penalizing individuals, companies, or nations that engage in illegal activities or pose a threat to international stability. These sanctions can range from asset freezes and travel bans to trade embargoes. Politically Exposed Persons (PEPs) are individuals who hold high-level public roles or are associated with those in power, such as senior politicians, military leaders, or oligarchs. Due to their positions, PEPs are often more vulnerable to corruption and financial misconduct, making them key targets in asset tracing and recovery.
The Russian sanctions, particularly, have underscored the importance of these measures in modern geopolitics. Since 2022, the U.S., EU, UK, and other Western governments have levied sweeping sanctions against Russian individuals and entities, aiming to disrupt the financial networks supporting the Russian government. This includes freezing billions in assets held by Russian PEPs abroad. However, the targeting of assets is not always straightforward, and as the enforcement of sanctions has ramped up, issues of wrongful targeting and the misidentification of assets have arisen.
The Impact of Russian Sanctions on Asset Tracing and Recovery
The sanctions against Russia have created significant challenges in the world of asset tracing and recovery, particularly in uncovering assets linked to Russian oligarchs and government officials. The complexities of these cases stem from the sophisticated methods used to hide wealth and the transnational nature of these networks. But an emerging issue is the wrongful inclusion of certain individuals and the misidentification of assets as belonging to sanctioned individuals.
1. Complex Asset Structures and the Wrongful Linking of Assets
Russian oligarchs and PEPs often use sophisticated legal and financial structures to conceal their assets, including offshore accounts, shell companies, and proxy ownership. However, this can sometimes lead to assets being wrongly linked to sanctioned individuals. In some cases, assets owned by legitimate businesses or individuals are mistakenly frozen due to an indirect connection to a sanctioned person.
For example, complex ownership structures may cause authorities to freeze assets of individuals who share business interests with sanctioned figures but have no direct involvement in illicit activities. This has happened in cases where joint ventures or partnerships—some of which were initiated long before sanctions were imposed—were misinterpreted as attempts to shield assets from recovery efforts.
2. Shifting Assets to Friendly Jurisdictions and Legal Challenges
In response to sanctions, many Russian PEPs have moved their wealth to jurisdictions that are either neutral or supportive of Russia, such as the United Arab Emirates or Turkey. However, some assets have been mistakenly linked to sanctioned individuals simply because they are in these jurisdictions, leading to wrongful asset freezes. Asset recovery professionals now face the challenge of distinguishing legitimate holdings from those belonging to sanctioned figures.
Another issue arises when innocent individuals are mistakenly included in sanctions lists, which can severely damage their reputations and financial standing. As a result, several Russian businesspeople and investors have challenged their inclusion in sanctions lists in court. For example, some individuals have been able to prove they had no direct ties to the Russian government or activities related to the Ukraine conflict, leading to their removal from sanctions lists.
3. Cases of Wrongful Targeting: Individuals Removed from Sanctions Lists
There have been notable cases of individuals who were wrongfully sanctioned and subsequently removed from sanctions lists. One prominent example is that of Roman Abramovich, the former owner of Chelsea Football Club, who has taken steps to distance himself from Russian politics and has even engaged in mediation efforts between Russia and Ukraine. Despite initial sanctions, Abramovich’s efforts led to a reassessment of his situation, and some of his assets have been unfrozen. His case highlights the nuances in determining which individuals are truly tied to a sanctioned regime and which may have been wrongfully targeted.
Another example is Mikhail Fridman, a Russian-born billionaire with substantial business interests in Europe. Fridman has long maintained that he has no close ties to the Kremlin, but he was still targeted by sanctions due to his wealth and public profile. Fridman launched legal challenges in European courts to contest his inclusion, claiming that he was wrongfully sanctioned. His case continues to be a subject of debate, as courts weigh the evidence of his political connections versus his claims of independence from the Russian government.
4. Asset Freezes and the Burden on Businesses
Another trend related to Russian sanctions is the freezing of assets belonging to businesses that operate globally but have Russian shareholders or investors. In some cases, multinational companies have had their operations disrupted because of minority stakes held by Russian PEPs or sanctioned entities. These businesses, which may be based outside Russia and have no direct involvement in Russian politics, find their assets frozen or their access to international banking severely limited.
This has led to significant legal challenges as these companies seek to differentiate themselves from the sanctioned individuals or entities connected to them. Asset tracing professionals must now navigate the intricate web of ownership to ensure that only assets truly connected to sanctioned persons are frozen, while legitimate businesses can continue their operations.
The Role of International Cooperation and Regulatory Challenges
In cases involving wrongful targeting, asset recovery professionals face the delicate task of balancing enforcement with fairness. Mistakes in identifying assets or individuals linked to sanctioned PEPs can lead to reputational damage, significant financial losses, and protracted legal battles. The use of international frameworks, such as the European Union’s updated Global Human Rights Sanctions Regime, aims to address these complexities by ensuring better due diligence before imposing sanctions.
However, the legal challenges and lengthy processes for appealing wrongful sanctions can undermine the effectiveness of these measures. For individuals and businesses, the path to being removed from sanctions lists can be long and costly. International cooperation, transparency, and due process are key to ensuring that asset tracing and recovery efforts target the right individuals while minimizing wrongful enforcements.
How Asset Recovery Professionals Are Adapting
Given the increasing complexity of sanctions enforcement, asset recovery professionals are adapting their methods to ensure accurate tracing and fair targeting. Some strategies include:
- Forensic Financial Analysis: Investigators use detailed forensic audits to trace the flow of money and establish clear connections between assets and sanctioned individuals, minimizing the risk of wrongful seizures.
- Enhanced Due Diligence: Before freezing assets, investigators conduct enhanced due diligence on individuals and companies to ensure they are correctly linked to the sanctioned regime.
- Legal Recourse for Wrongful Targeting: Lawyers specializing in sanctions-related litigation are increasingly representing clients who believe they were wrongfully included in sanctions lists, advocating for their removal and the release of frozen assets.
Conclusion
The intersection of sanctions enforcement and asset tracing has become more intricate in 2024, particularly in the context of Russian sanctions. While these measures play a critical role in pressuring regimes and individuals engaged in unlawful activities, they also come with risks of wrongful targeting. As asset recovery professionals work to trace assets linked to Russian oligarchs and PEPs, they must also contend with cases where assets are wrongfully frozen, or individuals are mistakenly sanctioned.
The evolving landscape of sanctions enforcement underscores the need for international cooperation, transparency, and the use of sophisticated investigative techniques to ensure fairness in the asset recovery process. As more cases of wrongful targeting come to light, it is crucial for legal systems and governments to adapt and refine the tools they use to combat illicit financial flows while respecting due process and individual rights.
-
Trends Spotted in 2024: The Evolving Landscape of Asset Tracing and Recovery
As global markets evolve and technology continues to advance, the methods used to hide, trace, and recover assets are also changing. In 2024, several key trends have been reshaping the asset recovery landscape, driving innovation and changing how investigators and legal professionals approach complex cases. In this blog post, we’ll explore some of the most significant trends in asset tracing and recovery this year.

1. The Continued Rise of Cryptocurrencies and Digital Assets
One of the most transformative trends in asset recovery is the growing focus on cryptocurrencies and digital assets like NFTs (non-fungible tokens). These assets are increasingly being used to hide wealth, creating new challenges for asset recovery professionals. Cryptocurrencies are decentralized, pseudonymous, and often operate across borders, making them difficult to track using traditional financial investigation methods.
To address this, asset tracing experts are now developing advanced techniques to trace digital wallets and monitor blockchain transactions. Blockchain analytics tools have emerged to help investigators track the flow of funds across decentralized networks, linking digital wallets to individuals or entities. However, the volatility and anonymity inherent to the crypto world require constant adaptation by professionals seeking to recover assets hidden in these formats.
Regulatory bodies are also stepping up efforts to govern digital assets. Governments worldwide are implementing tighter regulations on cryptocurrency exchanges, improving transparency, and facilitating the recovery of misappropriated digital assets. As regulators catch up with the rapid pace of technological innovation, asset tracing in this space is expected to become more streamlined.
2. The Importance of Cross-Border Enforcement
In an increasingly globalized world, the complexity of cross-border asset recovery is growing, and cases now frequently involve multiple legal systems, international courts, and regulatory bodies.
To successfully recover assets from multiple countries, legal professionals must navigate a maze of international treaties and varying legal frameworks. Multilateral organizations, such as the United Nations Commission on International Trade Law (UNCITRAL) and the European Union, are playing an important role in promoting cross-border collaboration. The mutual recognition of judgments, enhanced cooperation between law enforcement agencies, and a focus on the recovery of assets linked to criminal enterprises are all becoming more prominent.
Collaboration among legal professionals, forensic accountants, and investigative firms is critical in these cross-border cases. By pooling resources and expertise across jurisdictions, professionals can more effectively locate and recover hidden or misappropriated assets, no matter where they are concealed.
3. The Use of AI and Big Data in Asset Tracing
Artificial intelligence (AI) and big data are revolutionizing asset tracing and recovery. Investigators are now using advanced AI-driven tools to sift through enormous amounts of financial data, identifying patterns, anomalies, and connections that might have been overlooked using traditional methods. These tools can process vast amounts of information in a fraction of the time it would take a human investigator.
AI-powered forensic accounting, due diligence, and fraud investigations allow professionals to analyze global financial transactions, identify red flags, and trace assets across complicated networks. Moreover, predictive analytics are now being used to anticipate fraud schemes and prevent the movement of assets before they disappear.
As AI and big data technology continue to develop, we can expect even more sophisticated tools to emerge in the asset recovery space, further enhancing the efficiency and accuracy of investigations.
4. The Influence of ESG on Asset Recovery
Environmental, Social, and Governance (ESG) factors are becoming increasingly influential in corporate decision-making, and they are also starting to impact asset recovery efforts. Investors, regulators, and consumers are putting pressure on businesses to meet ethical standards, and failure to do so can lead to financial penalties, reputational damage, and asset seizures.
Companies involved in environmental violations, corruption, or other ESG-related misconduct are facing heightened scrutiny from regulators. As a result, the recovery of assets linked to such violations is becoming more common. ESG violations, such as those involving environmental degradation or labor abuses, are often financially linked to fraudulent or hidden activities, providing an additional incentive for asset tracing and recovery professionals to pursue these cases.
5. Targeting Third-Party Enablers
One of the most significant trends in asset recovery today is the growing focus on third-party enablers. These are professionals, such as lawyers, accountants, bankers, and fiduciaries, who may knowingly or unknowingly help conceal or move illicit assets. Governments and regulators are increasingly scrutinizing these enablers, and recovery efforts are now targeting the professionals who facilitate the concealment of assets.
For example, financial institutions that fail to conduct adequate due diligence or assist in moving funds can be held liable for enabling money laundering or fraud. Legal actions against these third-party enablers are on the rise, as asset recovery professionals pursue both the assets and those who helped hide them.
6. Sanctions and Politically Exposed Persons (PEPs)
Global political instability has resulted in increased sanctions on individuals and entities linked to corrupt or criminal activities, particularly in regions such as Russia, China, and the Middle East. Sanctions enforcement and asset recovery efforts are becoming more intertwined, particularly when dealing with assets linked to Politically Exposed Persons (PEPs).
Tracing and recovering assets tied to PEPs often involves navigating complex legal frameworks and dealing with sanctioned individuals. Governments are tightening their controls on assets held by sanctioned persons, which makes the asset recovery process more intricate, especially when it involves offshore accounts and shell companies.
7. The Growing Role of Insolvency in Asset Recovery
Insolvency and bankruptcy proceedings are increasingly being used as a tool for asset recovery, particularly in cases where fraudulent transfers have occurred. Creditors are becoming more aggressive in pursuing assets hidden through insolvency mechanisms, such as fraudulent conveyances and voidable transactions. By leveraging insolvency law, creditors can unwind asset transfers and recover misappropriated funds, making this an effective strategy in complex recovery cases.
8. Collaboration Between Law Firms and Investigative Firms
The complexity of modern asset recovery cases has led to closer collaboration between law firms and specialized investigative firms. These firms use deep-dive forensic investigations to locate hidden assets, particularly those shielded by shell companies, trusts, or offshore structures. Legal professionals now rely heavily on these investigative partnerships to navigate the intricacies of global asset recovery.
Conclusion
Asset tracing and recovery in 2024 is evolving rapidly, driven by technological advancements, regulatory changes, and increasing globalization. As the methods used to conceal assets become more sophisticated, the tools and strategies used to recover them must keep pace. From the rise of digital assets and AI-driven investigations to the growing importance of ESG and cross-border enforcement, professionals in this field are adapting to a dynamic and challenging landscape. The future of asset recovery will be shaped by these trends, and those who can navigate this complexity will be best positioned to succeed.
-
Rudy Kurniawan Is Back: “Dr. Conti”, from Notorious Wine Fraudster to Cult Figure?
Introduction
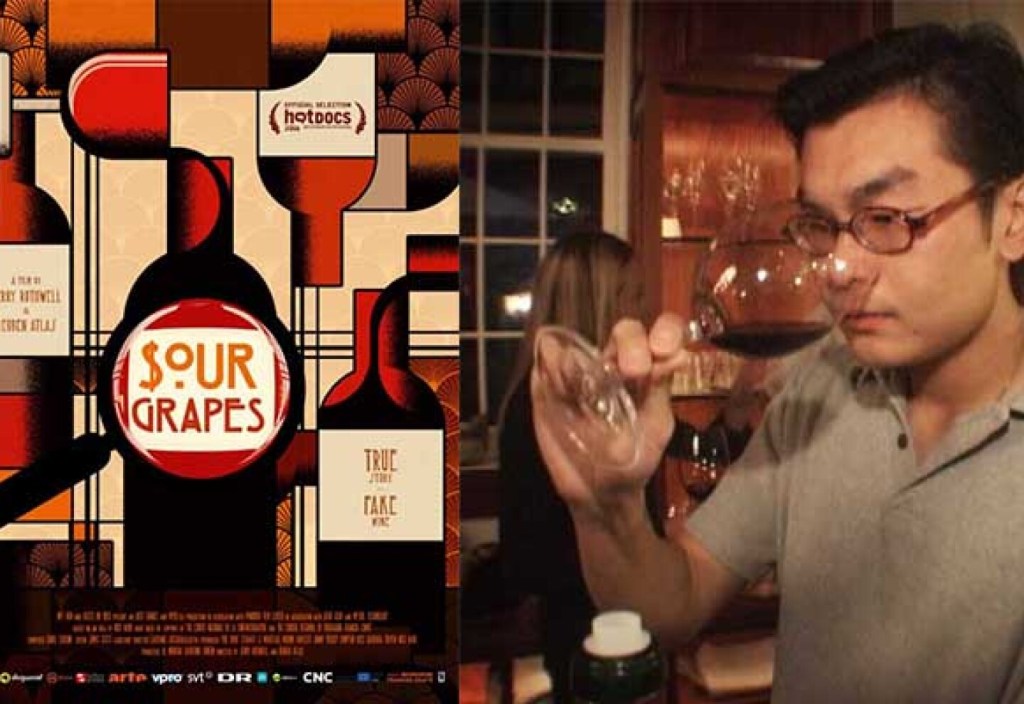
In the annals of wine fraud, few names stir as much intrigue and controversy as Rudy Kurniawan. Once a revered name among wine collectors, Kurniawan’s descent into notoriety as a master wine counterfeiter is as dramatic as it is unprecedented. His story, which inspired the 2016 Netflix documentary “Sour Grapes” by Jerry Rothwell and Reuben Atlas, offers a fascinating look at the intricacies of wine valuation and the fine line between genius and fraud. Now, in an unexpected twist, his past notoriety has transformed into a bizarre form of cult status. This piece delves into the rise, fall, and peculiar resurgence of Rudy Kurniawan.
Early Years and Rise to Fame
Born in Indonesia in 1976, Rudy Kurniawan moved to the United States in the late 1990s. He quickly made a name for himself in the wine community with his seemingly encyclopedic knowledge of vintage wines and an uncanny ability to source rare bottles. His deep knowledge of vintage wines and ability to source rare bottles earned him the nickname “Dr. Conti,” a nod to his fondness for wines from Domaine de la Romanée-Conti, one of Burgundy’s most esteemed vineyards. This title reflected his reputation as an expert in these highly sought-after wines. His charm and expertise won him entry into the inner circles of wine collectors and connoisseurs. By the early 2000s, Kurniawan was not just a respected figure in these circles; he was a trendsetter.
The Unraveling of a Wine Con
However, Kurniawan’s meteoric rise was built on a foundation of deceit. The first cracks appeared when experts noticed inconsistencies in his offerings. The tipping point came when Kurniawan attempted to auction bottles of Clos Saint-Denis from the Domaine Ponsot, which the winemaker claimed never existed for the vintages Kurniawan was selling. This led to investigations revealing that Kurniawan was mixing cheaper wines and re-bottling them as expensive vintages in his kitchen.
Conviction and Imprisonment
In 2013, the curtain was finally pulled back, and Kurniawan’s charade came to an end. He was convicted of selling millions of dollars worth of counterfeit wines and sentenced to 10 years in prison. The FBI estimated that he sold about $30 million in fraudulent wines, though the actual figure might be much higher. His conviction sent shockwaves through the wine world, shattering the trust and authenticity that is the cornerstone of wine collecting.
Unexpected Cult Status and Current Endeavors
Fast forward to 2023, following his release from prison and subsequent deportation to Indonesia, Rudy Kurniawan has re-emerged in the wine scene, but in a role that is as controversial as it is unexpected. He is now being sought after for his expertise in creating counterfeit wines, not as a means of deceit, but as a form of entertainment and curiosity.
In a bizarre turn of events, Kurniawan’s infamy has become his selling point. He was reportedly hired to create fake versions of prestigious wines for a private event in Singapore, where guests compared his forgeries to the real bottles. Surprisingly, many preferred Kurniawan’s versions. This incident highlights a surreal facet of the wine world where the line between authenticity and artistry blurs.
Reflections on the Wine World
The story of Rudy Kurniawan is more than a tale of crime and deception. It raises fundamental questions about value, authenticity, and the perception of luxury. His ability to fool connoisseurs and experts for years challenges the notion of what makes a wine valuable—is it its taste, its rarity, or the story behind it?
Conclusion
As Kurniawan continues to create his “masterpieces,” albeit now transparently fake, he paradoxically garners a following that admires his skills and the audacity of his past actions. While some view his current activities with disdain, others see them as a form of art, further muddling the already complex relationship between authenticity and value in the wine world.
Rudy Kurniawan’s journey from a respected wine connoisseur to a convicted fraudster and now to a cult figure is a fascinating study of human psychology, luxury perception, and the fine line between genius and infamy. As he continues to navigate his notorious legacy, the wine world watches with a mix of apprehension, curiosity, and, perhaps, a hint of admiration for the audacity of his artifice.
-
The Projected EU Sanctions on Russian Diamonds and the Mechanisms of Diamond Traceability
Photo by u0422u0430u0442u044cu044fu043du0430 u0427u0435u0440u043du044bu0448u043eu0432u0430ud83cudf52 on Pexels.com Introduction
The impending decision by the European Union to impose sanctions on Russian diamonds from 2024 signifies a pivotal shift in the global diamond industry. These sanctions, part of a broader set of measures against Russia, not only respond to geopolitical tensions but also highlight the increasing importance of ethical sourcing and traceability in the diamond trade. This development makes it imperative to explore the mechanisms available for tracing diamonds, particularly focusing on the innovative use of blockchain technology.
The EU’s Stance on Russian Diamonds
In the ever-evolving landscape of international relations, the EU’s stance on Russian diamonds sends a resounding message against the financing of conflict and unethical practices in the gemstone market. Initially, the EU implemented a ban on the export of luxury goods, including diamonds, to Russia, with exceptions made for industrial purposes. This was a significant move, considering the importance of the Russian diamond industry on a global scale. Later, the EU proposed a more direct action – a ban on the import of Russian diamonds and diamond jewelry starting January 1, 2024. This embargo aims to sever one of the world’s largest diamond producers from a crucial market. It’s a strategic economic sanction that underscores the EU’s commitment to ethical international trade practices.
The Importance of Diamond Traceability
Diamond traceability has never been as vital as it is today. With consumers growing increasingly conscious about the ethical implications of their purchases, the diamond industry faces mounting pressure to authenticate the origin and journey of its products. Traceability is not just about ensuring diamonds are conflict-free; it’s also about compliance with international regulations, such as the Kimberley Process, and adding intrinsic value to the consumer. However, achieving effective traceability is challenged by the complex nature of the diamond supply chain, where stones often change hands multiple times across different countries.
The Emerging Role of Blockchain in Diamond Traceability
Blockchain technology has emerged as a transformative force in ensuring diamond traceability. Its application in the diamond industry exemplifies how modern technology can revolutionize traditional practices:
Decentralized Ledger
Blockchain operates on a decentralized ledger system, recording data across numerous computers. This decentralized nature makes it exceedingly difficult to tamper with data, ensuring a reliable and unalterable history of each diamond’s journey.
Transparency and Security
Blockchain’s transparent nature ensures that every transaction or change in ownership of the diamond is visible and traceable by all parties, while also being secure against fraud and manipulation.
Unique Identification
Each diamond can be assigned a unique digital ID on the blockchain, detailing its characteristics and journey. This digital ID becomes a cornerstone in the tracking process, providing a comprehensive history of the stone.
Tamper-Proof Records
Once information about a diamond’s journey is entered into the blockchain, it cannot be altered. This feature creates a tamper-proof and trustworthy record of the diamond’s history.
Enhancing Consumer Trust
Blockchain technology is instrumental in providing consumers with a detailed history of diamonds, thereby enhancing trust and engagement. Consumers can verify the ethical sourcing and authenticity of their purchases, fostering a sense of responsibility and transparency in the diamond market.
Industry Initiatives: Tracr™ and GIA Diamond Origin Report
Tracr™ – Pioneering Blockchain in Diamond Traceability
Tracr™, an initiative by De Beers Group, stands as a significant development in diamond traceability. Utilizing blockchain, Tracr™ creates a secure digital trail for each diamond. It seamlessly integrates with the diamond industry’s existing processes, offering each diamond a unique digital ID that encompasses a wealth of information about its provenance and characteristics.
GIA Diamond Origin Report – A Leap in Diamond Verification
The Gemological Institute of America (GIA) has also made strides with its Diamond Origin Report. This service goes beyond traditional quality assessment by providing verified information about the diamond’s geographic origin. The report enhances consumer confidence and supports the ethical sourcing of diamonds, catering to the increasing demand for transparency in the diamond industry.
Addressing Challenges and Seizing Opportunities
Despite these advancements, significant challenges remain in ensuring complete traceability. The mixing of diamond supplies and the complexities of the global supply chain pose substantial hurdles. However, these challenges also present opportunities for innovation and collaboration within the industry. The continuous development of technologies like blockchain and the collective effort of industry players can pave the way for more robust traceability mechanisms.
The Future of Diamond Traceability
Looking ahead, the proposed EU sanctions on Russian diamonds and the evolving mechanisms for diamond traceability, especially through blockchain technology, are set to play a crucial role in shaping a more ethical and transparent diamond industry. This evolution is not just a response to regulatory requirements but also a reflection of changing consumer preferences and the industry’s commitment to ethical practices.
As we advance, the collaboration between governments, industry players, and consumers will be vital in ensuring the success of these initiatives. There is a growing recognition that the value of diamonds goes beyond their physical attributes; it also encompasses the story of their journey.
-
Cyberfraud: What Responsibility Do Banks and Telecommunication Companies Have?
Photo by Anna Shvets on Pexels.com Introduction
Cyberfraud is an increasingly frequent and serious problem that affects both customers and financial institutions. It involves a set of illegal techniques used by cybercriminals to obtain personal and banking information from users, access their accounts, carry out unauthorized transactions, or extort them by locking their electronic devices. Some of the most common types of banking cyberfraud include phishing, vishing, smishing, spoofing, malware, and SIM swapping.
Given this situation, the question arises as to what responsibility banks and telecommunication companies have in cases of cyberfraud, and what rights affected customers have to claim back the money that has been stolen or compensation for the damages and losses caused by this cyberattack.
Responsibility of Banking Entities
According to Spanish law, banks can be held responsible for cases of cyberfraud, especially when it involves phishing, a technique used by criminals to obtain personal and banking information from users by sending false messages that impersonate a legitimate entity.
The Law 16/2009 on payment services states that payment transactions not authorized by the account holder must be automatically reimbursed to them, provided that the customer has not acted fraudulently or with gross negligence, or has immediately reported the unauthorized transfer to the bank.
In addition, Regulation (EU) 2015/847 on information accompanying fund transfers imposes a series of obligations on payment service providers regarding control and monitoring of payments, such as verifying the identity of the beneficiary and refusing to execute the transfer in case of discrepancies. Therefore, if the bank fails to comply with these obligations, it can be responsible for the damages and losses caused to the customer by cyberfraud and must return the stolen money plus accrued interest.
However, the responsibility of the bank is not limited to phishing but can extend to other types of cyberfraud that also involve unauthorized access to customers’ accounts, such as vishing, smishing, spoofing, or malware. These types of cyberfraud can cause damage to both the customer and the bank, so it is important that both adopt security and prevention measures, such as verifying the authenticity of messages or calls received, not sharing their data or access keys with anyone, using antivirus and firewalls, updating their operating systems and applications, and reporting any incidents or suspicions of fraud.
Assessing User Responsibility and Bank Liability in Online Banking Security Breaches
Decisions from various Spanish courts address the issues of negligence and liability in the context of online banking security.
The courts have highlighted the significant negligence on the part of plaintiffs in safeguarding their online banking credentials, with a particular focus on the failure to adequately explain how fraudulent transactions were executed or how fraudsters managed to maintain control over their mobile devices.
The rulings emphasize the user’s imperative duty to protect their personalized security credentials and to avoid sharing them with third parties. Reckless sharing of such sensitive information is considered gross negligence, absolving the bank from any liability.
Furthermore, the judgments note that payment service providers may be exempt from liability if it can be shown that the incident occurred due to the customer’s intentional or grossly negligent actions.
Discussions within these rulings include the methods by which criminals may clone SIM cards through various cybercrimes, such as pharming, hijacking, or by installing malware-ridden apps that capture comprehensive data from the compromised device.
These cases underscore the essential need for user diligence in protecting personal data and access credentials in online banking environments, setting forth the conditions under which banks may be absolved of responsibility, contingent on the proven negligence of the customer.
Responsibility of Telecommunication Companies
Another type of cyberfraud that has become significant in recent years is SIM swapping, which involves duplicating the SIM card of a person’s mobile phone to impersonate their identity and access their bank accounts or other services that require SMS verification.
In this case, the responsibility of the bank may be reduced or excluded if it has complied with the security and prevention measures established by the regulations, such as sending unique and random confirmation codes to the customer or rejecting suspicious operations.
However, the responsibility of the telecommunication company can be increased or aggravated if it has not guaranteed the confidentiality and security of its customers’ data and has facilitated the SIM duplication without the consent or verification of the holder.
The Spanish Data Protection Agency (AEPD) has imposed multimillion-euro fines on the main mobile operators for this reason. Moreover, the courts have sentenced some telecommunication companies to compensate customers who have suffered this type of fraud, in cases where their SIM card was duplicated, and money was stolen from their bank account.
Joint and Several Liability of Banks and Telecommunications Companies (Including Internal Recourse Actions): Addressing SIM Swapping Cases in Spanish Courts
In SIM swapping cases, Spanish courts have established that entities, such as banks and payment service providers, may be held responsible under data protection laws if their actions, or lack thereof, facilitated financial fraud.
If a SIM card is illegally duplicated and used in fraudulent activities, not only the telecommunication company that carried out the duplication but also financial institutions that failed to implement adequate security measures might be implicated.
These entities can be deemed jointly and severally liable for the resulting damages to the affected parties.
However, the courts also recognize the right of these entities to pursue internal recourse actions against each other to recover contributions to any compensation paid to the victim. This legal principle acknowledges the complex interplay of responsibilities among different service providers in protecting against and responding to data breaches and fraudulent acts.
Conclusion
The multifaceted nature of banking cyberfraud, encompassing phishing, vishing, smishing, spoofing, malware, ransomware, and SIM swapping, necessitates a collaborative and vigilant approach from both financial institutions and telecommunication companies.
Spanish case-law has established a framework of responsibility where banks and telecom companies are accountable for ensuring the security of their customers’ data and transactions. In cases of negligence or failure to adhere to regulatory standards, these entities face the possibility of being held liable for the damages suffered by the victims of cyberfraud.
Particularly in SIM swapping incidents, the courts have underscored the concept of joint and several liability, where both telecommunication companies and financial institutions can be held responsible if their actions have directly or indirectly facilitated the fraud. This approach not only emphasizes the need for stringent security measures and compliance with data protection laws but also highlights the importance of customer awareness and precaution in safeguarding their personal and financial information.
Ultimately, these rulings serve as a critical reminder of the shared responsibilities in the digital age, urging banks, telecom companies, and customers to remain proactive and cooperative in combating the evolving threats of banking cyberfraud.
-
Section 1782’s Influence and UNCITRAL’s Progressive Stance on International Asset Recovery
Photo by Pixabay on Pexels.com Introduction
In the realm of international asset tracing and recovery, the landscape is marked by a paucity of efficient legal mechanisms for cross-border cooperation. This gap is highlighted by the unique characteristics of Section 1782 of the United States Code, a provision that stands out for its direct approach in assisting foreign legal proceedings. This scenario set the stage for the United Nations Commission on International Trade Law (UNCITRAL) to initiate comprehensive work in this area, particularly focusing on insolvency law.
Section 1782 of the US Code: A Pioneering Tool in International Law
Section 1782(a) represents a novel approach in international legal cooperation. This U.S. statute allows foreign litigants to directly request U.S. courts to assist in gathering evidence for use in foreign proceedings. Its uniqueness lies in its capacity to bypass traditional diplomatic channels, offering a more expedient and direct method for evidence collection. This feature, while specific to the U.S. jurisdiction, has had a ripple effect in highlighting the need for similar mechanisms in international law, especially in asset tracing and recovery.
The International Gap and UNCITRAL’s Response
The advent of Section 1782 underscored the scarcity of comparable legal tools in the international arena. It spotlighted the challenges in cross-border asset tracing and recovery, emphasizing the necessity for a more unified and effective global legal framework. Recognizing this imperative, UNCITRAL embarked on an initiative to address these challenges, with a particular focus on insolvency law.
UNCITRAL’s Approach to Asset Tracing in Insolvency
UNCITRAL’s work in insolvency law has been geared towards creating harmonized legal standards and practices. By developing guidelines and resources for asset tracing and recovery in insolvency cases, UNCITRAL aims to bridge the gaps in international cooperation. Its efforts include compiling detailed inventories of tools and creating best practice guidelines, thus facilitating a more coherent approach to cross-border insolvency proceedings.
The Synergy Between Section 1782 and UNCITRAL’s Initiatives
The existence of Section 1782 has not only highlighted the potential for direct legal assistance in international law but also inspired broader discussions about improving international cooperation in asset recovery. UNCITRAL’s initiatives, while not directly replicating Section 1782, take cues from its direct and effective approach. The commission’s focus on insolvency law serves as a strategic entry point, considering the complexities and international implications often inherent in insolvency cases.
Digital Assets and Emerging Challenges
In an era of rapid technological advancement, UNCITRAL’s work also addresses the burgeoning challenges related to digital assets. Cryptocurrencies and blockchain technology, for instance, have introduced new complexities in asset tracing, necessitating adaptive legal responses. UNCITRAL’s efforts in this domain are crucial for ensuring that international insolvency law keeps pace with technological evolution.
The Future of International Legal Cooperation
Looking ahead, the interplay between national tools like Section 1782 and international efforts spearheaded by bodies like UNCITRAL is likely to shape the future of asset recovery in international law. The need for effective, harmonized legal frameworks is increasingly pressing in a globalized economic landscape marked by intricate financial transactions and technological advancements.
Conclusion
The influence of Section 1782 in the U.S. has been a catalyst for global legal developments in asset tracing and recovery. UNCITRAL’s response, particularly in the area of insolvency law, signifies a crucial step towards establishing more robust and coherent international legal mechanisms. As this field continues to evolve, the collaborative efforts of national and international bodies will be key in navigating the complexities of cross-border asset recovery.
-
The ‘Spanish Saga’ in the Antin case and beyond: award recognition and asset recovery in EU investment arbitration
Photo by Vlad Ioan on Pexels.com This article was first published in the newsletter of the Asset Recovery Committee of the International Bar Association
Introduction
Recently, on 24 May 2023, the High Court of London issued its long-awaited decision in the Antin case. The High Court dismissed the appeal against the registration (ie, the recognition) of the International Centre for Settlement of Investment Disputes (ICSID) award that ordered Spain to pay €120m in favour of Infrastructure Services Luxembourg SÀRL and Energia Termosolar BV, for breach of its obligations under the Energy Charter Treaty (ECT). Spain opposed the recognition of the ICSID award invoking its sovereign immunity, which in turn was based on the Achmea and Komstroy doctrines developed by the Court of Justice of the European Union (CJEU).
Appropriately, the High Court of London referred to the analysis of these doctrines as ‘the EU law question’. In short, what the court had to determine was whether, based on the principle of primacy of EU law, Spain held sovereign immunity from jurisdiction that invalidated ICSID’s competence to resolve such disputes through arbitration and, consequently, whether it was appropriate to deny recognition of the award.
The High Court of London dismissed Spain’s opposition, on the grounds that the primacy of EU law does not render Spain’s (or the UK’s) obligations under the ICSID Convention or ECT ineffective ‘as a matter of international law’. Thus, the High Court of London considered that Spain, by signing the ICSID Convention and ECT, waived its immunity from jurisdiction and submitted to arbitration for dispute resolution in this matter.
Does EU law have primacy over international law?
The CJEU established in its decisions on the Achmea and Komstroy cases that investment arbitration established both in bilateral investment treaties between EU states and in multilateral treaties signed by them, are contrary to the ‘primacy’ of EU law.
The CJEU considered that investment arbitration leaves the final word on the application of EU law to an arbitral tribunal and not to the CJEU, which violates the exclusive competence of the latter for the interpretation and application of EU law.
As a matter of principle, ‘primacy’ of EU law means that its application prevails over the national law of EU Member States. Domestic law of an EU Member State that contradicts EU law must be disregarded, giving priority to the application of EU law.
However, can this primacy also be invoked with respect to international law? May EU Member States invoke EU law to render ineffective the obligations imposed on them by international law, in the case at hand, the ICSID Convention and the ECT, that these same EU Member States have freely signed? The High Court of London understands that they may not.
Certainly, from the perspective of an EU Member State, international law is ‘domestic law’, from the moment that EU Member States have incorporated their international obligations into their legal system. However, the ICSID Convention and the ECT also impose international obligations on States that are not members of the European Union (EU), such as, for example, the UK. Hence, the High Court wonders whether EU law prevails over the ICSID Convention and the ECT ‘as a matter of international law’ because it is the only link between EU Member States and non-Member States in such matters.
In this respect, the High Court of London invokes the Vienna Convention on the Law of Treaties Article 26 (‘pacta sunt servanda’) and Article 27 (ie, the prohibition of invoking an internal rule to render ineffective an obligation arising from an international treaty) to reject the primacy of EU law over the ICSID Convention and the ECT. Consequently, the High Court of London considers that it cannot either rely on the alleged primacy of EU law to render ineffective the obligations that arise from the ICSID Convention and the ECT, of which the UK is also a party.
That is, according to the High Court of London, international law does not allow it to disregard the ICSID Convention or the ECT based on EU law. In other words, EU law is not a kind of ‘supra-international’ order that prevails over the international obligations of Member and non-Member States of the EU.
A controversial topic
This decision of the High Court of London has been received with special joy in common law jurisdictions, particularly in England, which from now on can present itself as a ‘safe haven’ in which to execute awards issued in investment arbitrations that the EU Member States refuse to recognise.
In the author’s opinion, the Achmea and Komstroy doctrines should not render unenforceable the arbitral awards issued in arbitrations that started before the elaboration of these doctrines by the CJEU. Rather, these doctrines impose on EU Member States the obligation to walk away from the international treaties that contravene EU law, as interpreted by the CJEU. This is what Spain has recently done denouncing the ECT.
However, this denunciation should not have ‘retroactive’ effects. Therefore, arbitral awards issued in accordance with the ECT while it was binding on Spain should be respected and complied with. (By the way, this opinion is exactly the opposite to what Spain and the EU are currently defending. However, since this is my honest point of view, I have no problem expressing it.)
The topic remains a controversial one. In fact, the decision of the High Court of London has not been the only decision on identical or similar cases issued in common law jurisdictions outside the EU. Specifically, Australia and the United States have dealt with other recognition requests, both for the same award as in the Antin case and for other awards against Spain arising from renewable energy investment arbitrations.
However, although most of those decisions have been favourable to the claimant investors, this has not always been the case.
For example, the ‘Memorandum Opinion’ of 29 March 2023, issued by the US District Court for the District of Columbia in the case Blasket Renewable Investments LLC v The Kingdom of Spain, resolved the case in the opposite direction, indicating that the Achmea and Komstroy doctrines invalidated any arbitration agreement applicable and, consequently, the exception to jurisdictional immunity provided for in section 1605(a)(6) of the Foreign Sovereign Immunity Act, consisting of the existence of an arbitration agreement in favour of a private party, was not applicable. Consequently, according to the US District Court, the arbitral award was issued in violation of the jurisdictional immunity that protects Spain as a sovereign State and, therefore, cannot be either recognised or enforced in the US.
Currently, this decision is pending an appeal filed by the enforcing party.
Conclusion
The decision of the US District Court is an interesting example of the enormous uncertainty caused by the Achmea and Komstroy doctrines, as well as the different interpretations that still exist in the field of state immunity, even among common law jurisdictions, such as the US and the UK.
These differences in interpretation are aggravated by the lack of validity of the 2004 United Nations Convention on Jurisdictional Immunities of States and Their Property, which the US has not even signed and which the UK has signed but not ratified (unlike Spain, which did ratify this Convention in 2011, although it has not entered into force as the minimum of 30 ratifications required for this purpose in the Convention itself has not been reached).
On the other hand, one can expect that these different interpretations regarding the scope of jurisdictional immunity may also translate into differences in interpretation regarding the scope of execution immunity, and consequently, to the efforts of tracing and recovering of sovereign assets.
This will continue to affect the effectiveness of the awards and will continue to highlight the need for greater harmonisation of asset recovery at an international level, especially when it comes to its relations with sovereign immunities.
-
Journalists will be allowed to “stick their noses” into UBO registers. Right or wrong?
Photo by Pixabay on Pexels.com The debate around UBO registers drags on.
As anticipated, Spain just launched its new UBO register (“UBOR”), adapted to the CJEU’s ruling of November 22, 2022.
As is well known, such ruling declared that allowing access to UBORs to the general public in all cases was contrary to the right to privacy and to the protection of personal data.
In addition, some observers had criticized early on that unrestricted access to UBORs would jeopardize effective asset tracing and recovery.
In the aftermath of the CJEU ruling, EU countries have had to adapt their regulation. Spain has been no different.
Who can access the new Spanish UBOR?
The new Spanish UBOR, according to its regulation enacted last July, which will enter into force next September, will allow access to:
- National authorities and of other EU Member States with competences in the prevention, detection, investigation and prosecution of terrorist financing, money laundering and predicate offenses; as well as national and EU authorities that manage, verify, pay or audit European Funds.
- Professionals with reporting obligations under AML regulations (financial institutions, investment firms, Notaries, lawyers, tax advisors, to name but a few), in order to comply with their obligations regarding the identification of the beneficial owner.
- Other persons with a legitimate interest.
What is a “legitimate interest” and who has it?
Interestingly, the regulation does not define the meaning of “legitimate interest”.
However, the regulation does say that legitimate interest shall be presumed in the case of:
- Media outlets and
- Civil society organizations related to the prevention and fight against money laundering and financing of terrorism.
My thoughts
Yes, of course, both media outlets and civil society organizations are important to combat fraud and corruption.
But isn’t this equivalent to allowing unrestricted access to UBORs , which is precisely the most criticized aspect of former UBOR regulations?
What is the difference between allowing access to the general public and allowing it to journalists and to “civil society” entities?
I personally believe there is no difference and that the quality of information available at the UBOR will suffer as a result.
Access to the UBOR should be allowed only to authorities and to professionals with reporting duties, i.e. those who need access to the data on the beneficial owner to perform their legal obligations.
Your thoughts?
This is certainly a controversial topic. Feel free to comment below.
-
How to enforce crypto-related decisions in Spain?
Photo by David McBee on Pexels.com This article was originally published at ICC FraudNet’s 2023 Global Annual Report: “Fraud and Asset Recovery in an Unstable World“, under the title “What about volatility? Enforcement of crypto-related decisions in Spain“. ICC FraudNet’s Global Report is a compilation of 28 original articles authored by 52 contributors beloging to the ICC FraudNet network, from some 20 jurisdictions, which cover the hottest current issues related to fraud and asset recovery.
Introduction
How to enforce an arbitral award ordering the refund of cryptocurrencies and similar digital assets?
We deal here with the possibilities at the disposal of a judgment or award creditor to obtain the refund in kind of crypto assets and digital assets during enforcement proceedings in Spain.
We explore the enforcement orders that Spanish Courts may issue and the existing alternatives when those orders fail to provide with the return in kind of the digital assets.
In particular, we analyze the risk of volatility and the instruments at the disposal of the creditor to reduce it according to Spanish law.
Request of legal opinion: a case-study
CryptoABC obtained an international arbitration award against the Spanish company XYZTechno.[1]
In that award, XYZTechno was ordered to return to CryptoABC a certain amount of digital assets, consisting of cryptocurrencies and various types of tokens, which CryptoABC had provided as interest-free funding to XYZTechno.
CryptoABC has asked for our opinion about the possibility to enforce such award in Spain.
CryptoABC is interested in tracing and recovering those digital assets, wherever they may be.
Bearing in mind that the arbitral award ordered XYZTechno to refund those digital assets in kind -and not their monetary equivalent-, CryptoABC has asked us to consider whether Spanish courts may issue disclosure and attachment orders, addressed both to the debtor and to third parties that may lead to:
- Ascertaining the crypto exchange where those digital assets may be deposited.
- Making sure that those digital assets are returned to CryptoABC. CryptoABC is also interested in learning more about the enforcement alternatives under Spanish law, in case the disclosure and attachment orders fail, i.e., they do not lead to the tracing and recovery of the digital assets.
Also, and crucially, CryptoABC is asking what protection Spanish law has to offer against the risks arising from the volatility of such assets, meaning, who bears the risk of potential loss in value of those digital assets between the date when they were delivered to XYZTechno and the time when those same assets will be possibly returned to CryptoABC.
In this article, we explore the Spanish legal framework to the extent necessary to answer those questions and provide insight in this particularly topical area.
Background
CryptoABC is a crypto exchange, i.e., a company dedicated to the trade and custody of cryptocurrencies and other digital assets. As such, it enjoys a solid reputation as a safe and reliable operator in the market.
XYZTechno is a market leader delivering liquidity solutions to blockchains. In this capacity, it reached an agreement with CryptoABC to provide market maker services[2] on one of the cryptocurrency exchange platforms developed by CryptoABC, called “ABC SuperExchange”.
To help it launch its services as a market maker, CryptoABC provided XYZTechno with interest-free funding (via the signature of several Loan Agreements) consisting of exact quantities of cryptocurrencies and digital assets (payment and utility tokens)[3] that XYZTechno would have to return.
At one point, CryptoABC requested TechnoXYZ to return the exact quantities of the cryptocurrencies and digital assets loaned at TechnoXYZ’s account in ABC SuperExchange. TechnoXYZ failed to comply with this request, which led the parties to arbitration. A sole arbitrator was appointed to handle the dispute.
The object of the refund: digital assets, or its equivalent initial value in fiat currency?
This was one of the critical issues of the dispute. CryptoABC argued it provided funding in the form of an exact quantity of digital assets.
CryptoABC further claimed that XYZTechno had to restitute this interest-free funding in the exact same quantities as received, in conformity with the parties’ intention that the funding should always remain the property of CryptoABC and that XYZTechno would bear the risk of losing it.
XYZTechno argued that funding had to be repaid based on its initial value in Euro, and not token-for-token.
The consequences of one option or the other are obvious. If the sole arbitrator was to order that the funding had to be refunded based on its initial value in fiat currency (the currency used was Euro), the volatility risk of the digital assets would be borne by the funder, insofar as that initial Euro value would be equivalent, at the time of repayment, to an amount different from that which was the initial subject of the funding.
If, on the other hand, the sole arbitrator was to rule that the funding had to be repaid in the exact amount of digital assets originally received, the volatility risk would be borne by the borrower since, if it did not hold the digital assets received, it would have to purchase them on the market at their equivalent price in Euro at the time of repayment.
Photo by Alesia Kozik on Pexels.com What the award rules
The award rules that the parties intended the return of the digital assets on a token-for-token basis, and not on a monetary value basis. It further considered that the parties agreed on an obligation to return the funding received in the same asset and in the same quantity as received.
Can a Spanish Court issue disclosure and attachment orders to the debtor and third parties in relation to digital assets?
Considering that the award orders the restitution of digital assets in kind (and in the exact amount initially received), CryptoABC needs to know whether a Spanish court can, during enforcement of the award, issue disclosure and attachment orders to the award debtor and to third parties – aimed at learning about the whereabouts of such digital assets and to make them available to the Spanish court, for their delivery to the award creditor.
The answer to this question of Spanish law is affirmative.
A Spanish court may, according to the Spanish Code of Civil Procedure, issue disclosure orders to the award debtor and to third parties.
First off, the Spanish court may order the award debtor to disclose whether it keeps the received digital assets and where they are deposited; the Spanish court may also order the award debtor to make these digital assets available to the court for delivery to the creditor.
To third parties (e.g., cryptocurrency exchange platforms, where the digital assets may be under custody), the Spanish court may also request them to disclose whether they deposit those assets and, if applicable, to make them available to the court for delivery to the award creditor.
Limitations on the effectiveness of disclosure and attachment orders addressed to the award debtor and to third parties
Even though it is possible to issue orders both to the debtor and to third parties, the effectiveness of both types of order is potentially different, particularly in matters related to cryptocurrencies, whose place of deposit can be anywhere in the world.
On the one hand, the award debtor is fully subject to the jurisdiction of the enforcement court and must comply with its orders.
If he fails to do so, the Spanish court may impose coercive fines on him. In addition, repeated non-compliance with judicial disclosure orders, as well as incomplete or mendacious responses to such requests, may be criminal offences under the Spanish Criminal Code.
However, in the case of third parties and, particularly, in the case of crypto exchanges, one can expect that it will only be materially possible to force them to comply with the Spanish court’s orders if their domicile is Spain.
If their domicile is not Spain (as is usually the case for most crypto exchange platforms), there are generally no international instruments that would allow Spanish courts to force the third party to comply with such order.
In any case, the few legal instruments that may be considered are very difficult to apply in practice.
This is a considerable limitation to international asset tracing and recovery affecting all types of assets, both digital and non-digital.
Photo by Jonathan Borba on Pexels.com What enforcement options does the award creditor have if the debtor or third party fails to comply with the orders issued by the Spanish Court?
To answer this question, it is first necessary to analyse the legal nature of cryptocurrencies (which Spanish legislation names “virtual currencies”) and other digital assets (which Spanish legislation names “crypto assets”).
In relation to the former, Spanish regulations define them as “a digital representation of value, not issued nor guaranteed by a central bank or public authority, and not necessarily associated with a legally established currency, which does not have the legal status of currency or money, but which is accepted as a medium of exchange and can be transferred, stored or traded electronically”.
What is noteworthy about this definition is that virtual currencies do not have the legal status of “currency” or money under Spanish law.
As for digital assets or “crypto-assets”, Spanish financial regulations define them as the “digital representation of a right, asset or value that can be transferred or stored electronically, using distributed ledger technologies or other similar technology”.
It follows from this definition that crypto assets are purely electronic and decentralised assets.
It also follows that digital assets are fungible and, as such, likely to be used as a medium of exchange in economic transactions.
We must therefore conclude that the cryptocurrencies and other digital assets that are the object of the award have the legal nature, under Spanish law, of non-cash and fungible assets (as opposed to the so-called “NFTs” or Non-Fungible Tokens, which, by definition, have a different legal nature).
Therefore, the enforcement of any court or arbitral decision whose object is cryptocurrencies and other fungible digital assets will follow the legal regime of non-monetary enforcement and, specifically, that of the enforced delivery of generic or indeterminate assets. In other words, the delivery of cryptocurrencies and digital assets has the same legal procedural treatment as that of a kilo of rice or potatoes (also generic or indeterminate assets); as opposed to the regime of delivery of a Picasso painting (which would be a specific movable asset, non-fungible and, therefore, the legal-procedural equivalent of an “NFT”…).
Option 1: Attachment of the debtor’s assets to pay for the acquisition of the fungible digital asset
When the debtor has refused to comply with the order to deliver fungible (i.e., generic, or indeterminate) assets, Spanish law allows the award creditor to acquire such assets at the debtor’s expense.
For this purpose, the creditor may request the court to empower him to acquire them, ordering at the same time the attachment of sufficient assets of the debtor to pay for the acquisition.
Naturally, the attachment of sufficient assets will be made in the fiat currency governing the enforcement; typically, in Spain, such currency will be Euros, but it could be any other of legal tender.
Therefore, an interesting question is what value, or “exchange rate” in fiat currency, will be used to determine the exact amount of the debtor’s assets that will have to be seized to finance the acquisition of the cryptocurrencies and other fungible digital assets that are the object of the award.
Some of the (countless) possibilities could be: (i) the exchange rate at the time when they were delivered to the borrower; (ii) at the time when the breach occurred; (iii) at the time of the arbitration claim; (iv) at the time of the award; (v) at the time of enforcement; (vi) or at the time of the award creditor’s acquisition of such cryptocurrencies and digital assets.
The correct answer under Spanish law is the latter: the debtor’s assets will be seized according to their value in fiat currency at the time of acquisition of the digital assets by the award creditor during the enforcement of the award. In this way, the risk of volatility of the digital assets will rely on the award debtor and not on the award creditor.
The creditor will receive value in fiat currency of the digital assets at the time of purchase and can therefore buy the same exact number of cryptocurrencies and digital assets that were borrowed at the time by the award debtor.
Option 2: Request that the non-deliveryof the digital assets be replaced by the payment of a fair monetary compensation
Spanish law also contemplates the possibility of it becoming impossible to purchase the generic or indeterminate asset.
This possibility is relevant in the case of cryptocurrencies and digital assets, one of whose characteristics, in some instances, is their lack of liquidity. In certain cases, such lack of liquidity may make it impossible to find buyers and sellers of the cryptocurrency or digital asset in question (hence the importance of the “market maker” services that XYZTechno undertook to provide on the CryptoABC platforms).
In these cases, Spanish law provides that the impossibility to deliver the asset should be replaced by the payment of a fair pecuniary compensation. What should the amount of such compensation be?
In our opinion, the compensation should cover, on the one hand, the value in fiat currency of the undelivered cryptocurrencies and digital assets (at the time when such compensation is calculated, i.e., at the time of the failed attempt to purchase them).
On the other hand, the compensation should cover any other demonstrable damages that the creditor has suffered because of the non-delivery of the cryptocurrencies and digital assets (i.e., direct and indirect damages).
To this end, the Spanish Code of Civil Procedure provides for a specific proceeding for the creditor to assert and prove the totality of damages suffered.
Conclusion
Spanish procedural law has not undergone any modification to adapt to the enforcement of court and arbitral decisions on the return of cryptocurrencies and other digital assets.
However, the current regulation is already relatively well-suited to certain aspects relating to the enforcement of judgments and awards involving the delivery in kind of such assets.
Spanish law provides that, in the absence of return in kind, the creditor may acquire the digital (fungible) assets at the debtor’s expense, seizing his other assets for the value, in fiat currency, necessary to purchase such assets at the time of the acquisition during the enforcement.
If this is not possible, Spanish law provides that the creditor may claim a fair monetary compensation from the debtor.
In either case, Spanish law protects the creditor against the inherent volatility of digital assets, allowing the creditor to recover the exact amount of digital assets recognised in the enforceable title, to be calculated in fiat currency at the time of the enforcement.
In this case, paradoxically, the latter option in the enforcement stage would reach the opposite solution to the one envisaged in the award, which rejected that the return of the digital assets could be made in fiat currency instead of being made in kind.
However, one must acknowledge there are no alternatives to the impossibility of recovering the digital assets in kind, other than converting them into their fiat currency value, be it to attach the debtor’s assets to assist in the purchase, or to pay to the award creditor a fair monetary compensation.
Therefore, the basic element to consider is protection for the award creditor against the volatility in the value of cryptocurrencies and digital assets.
As we have seen, Spanish law contemplates what seems a fair solution to this problem.
[1] This article refers to an actual case that is the subject of an international arbitral award issued in 2022 and administered by one of the world’s leading arbitral institutions. For reasons of confidentiality, the reference to the award is omitted. For the same reasons, the names of the parties and references to the products and services covered by the cryptographic platform have been modified and anonymized.
[2] “The term market maker refers to a firm or individual who actively quotes two-sided markets in a particular [asset], providing bids and offers (known as asks) along with the market size of each. Market makers provide liquidity and depth to markets and profit from the difference in the bid-ask spread. They may also make trades for their own accounts, which are known as principal trades.”, Market Maker Definition: What It Means and How They Make Money, Investopedia (Dec 8, 2022). This begs the question, why are market makers necessary? A market maker serves as a middleman or broker between the demand and supply for digital assets. Market makers provide liquidity in markets of digital assets, which ensures there is enough orders to buy and sell, while cryptocurrency exchanges offer the infrastructure that allows traders to operate. Market makers ensure traders can quickly and easily liquidate their holdings. Market makers are also necessary because they maintain price stability in a market with a somewhat small bid-ask spread. In addition to being seen as reputable and trustworthy by cryptocurrency traders, a market with price stability is an indication of significant liquidity, since it means that many participants are transacting, which in turn increases the market maker’s profit.
[3] “Payment tokens” are issued with payment medium functions on a given blockchain, while “utility tokens” grant the right to claim the provision of a service from issuers. There are also “security tokens”, which have equivalent functions to financial instruments (i.e. Initial Coin Offerings (ICOs) or other crypto-assets that represent tradable financial instruments, such as shares, bonds or rights to investment contracts).
-
Subscribe
Subscribed
Have a WordPress.com account? Log in now.

